


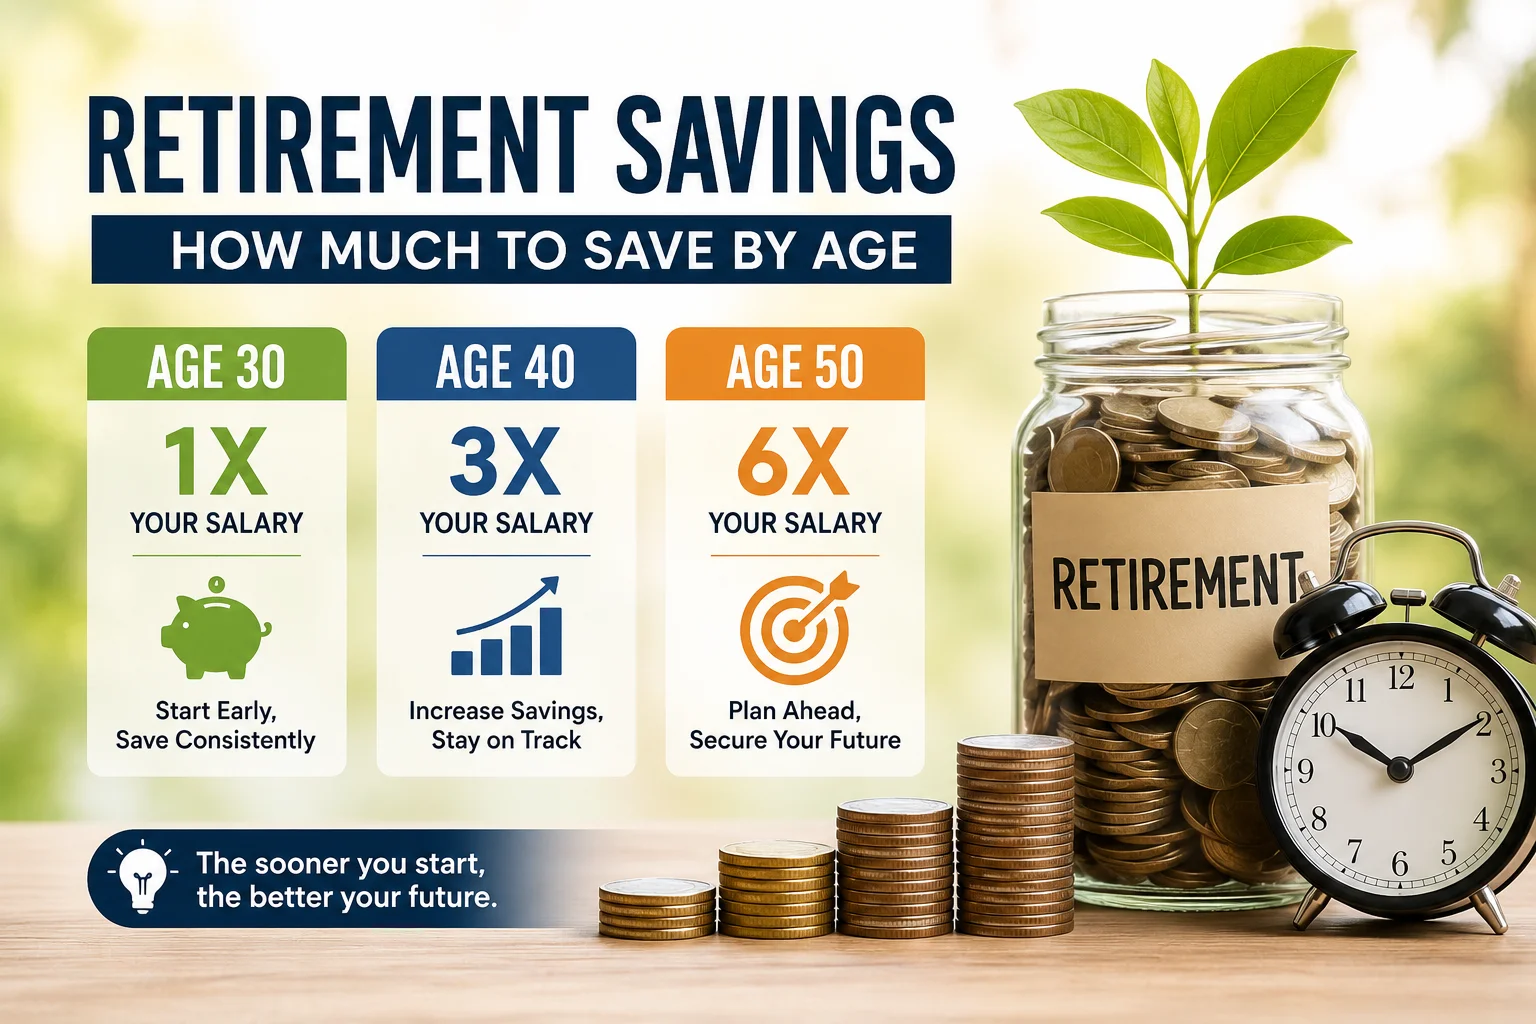
A widely used rule of thumb from Fidelity Investments is to have about 1 times your annual salary saved for retirement by age 30, 3 times by age 40 and 6 times by age 50, rising to 10 times by age 67. These are guidelines rather than rules: the right number for you depends on when you plan to retire, how much you expect to spend and what other income, such as Social Security, you will have. This guide explains each milestone with correct examples, the 2026 contribution limits and what to do if you are behind.
| Age | Savings target (times your salary) | Example on a $60,000 salary |
|---|---|---|
| 30 | 1x | $60,000 |
| 35 | 2x | $120,000 |
| 40 | 3x | $180,000 |
| 45 | 4x | $240,000 |
| 50 | 6x | $360,000 |
| 55 | 7x | $420,000 |
| 60 | 8x | $480,000 |
| 67 | 10x | $600,000 |
Why Does Starting Early Matter So Much?
Starting early matters because of compound growth: the returns your savings earn start earning returns of their own. Money invested in your 20s has 40 years or more to grow, so a small monthly amount early can end up worth more than a larger amount started later. You can test this with the SEC’s free compound interest calculator on Investor.gov. Starting early also gives you more time to recover from job losses, market falls or unexpected expenses.
How Much Should You Have Saved by Age 30?
By age 30, aim for about 1 times your annual salary. If you earn $50,000 a year, that means about $50,000 in retirement accounts. Many people in their 20s are also paying off student loans or building an emergency fund, so reaching this target exactly is less important than building the habit. Focus on these steps:
- Join your employer’s retirement plan, such as a 401(k), and contribute at least enough to get the full employer match. The match is extra money you lose if you do not claim it.
- Aim to save 15% of your income in total, including any employer match, and increase your rate each time you get a raise.
- Pay off high-interest debt such as credit cards. Our guide on how to pay off debt faster explains the main methods.
- Build an emergency fund so you do not have to withdraw retirement savings early.
Consistency matters more than size. Saving $250 every month from age 25 is far more powerful than waiting until you can afford $1,000 a month.
How Much Should You Have Saved by Age 40?
By age 40, the guideline is about 3 times your annual salary. On a $60,000 salary that is about $180,000, and on an $80,000 salary it is about $240,000. Your 40s are often your peak years for expenses such as housing and children, so it helps to automate your savings so they happen before you spend.
If you are behind at 40, it is not too late. Review your budget to find costs you can cut, and raise your savings rate step by step. For example, if you save 10% of your salary now, increase it to 11% or 12% this year, and add another percentage point with each raise. Many 401(k) plans offer an automatic increase feature that does this for you. Also check that your investments match your timeline: someone retiring in 25 years can usually take more stock market risk than someone retiring in five.
How Much Should You Have Saved by Age 50?
By age 50, the guideline is about 6 times your annual salary. On a $75,000 salary that is about $450,000, and on a $150,000 salary it is about $900,000. These figures can look very large, but remember that they include decades of investment growth, not just the money you put in.
At 50 you also become eligible for catch-up contributions, which let you save more each year than younger workers. This is the time to build a clear retirement plan around:
- Your expected retirement age.
- Your expected yearly spending in retirement, including housing and healthcare.
- Any debts you still need to repay.
- Your estimated Social Security benefit, which you can check with a free account at my Social Security.
- Other income, such as a pension, rental income or part-time work.
How Much Can You Contribute to Retirement Accounts in 2026 and 2027?
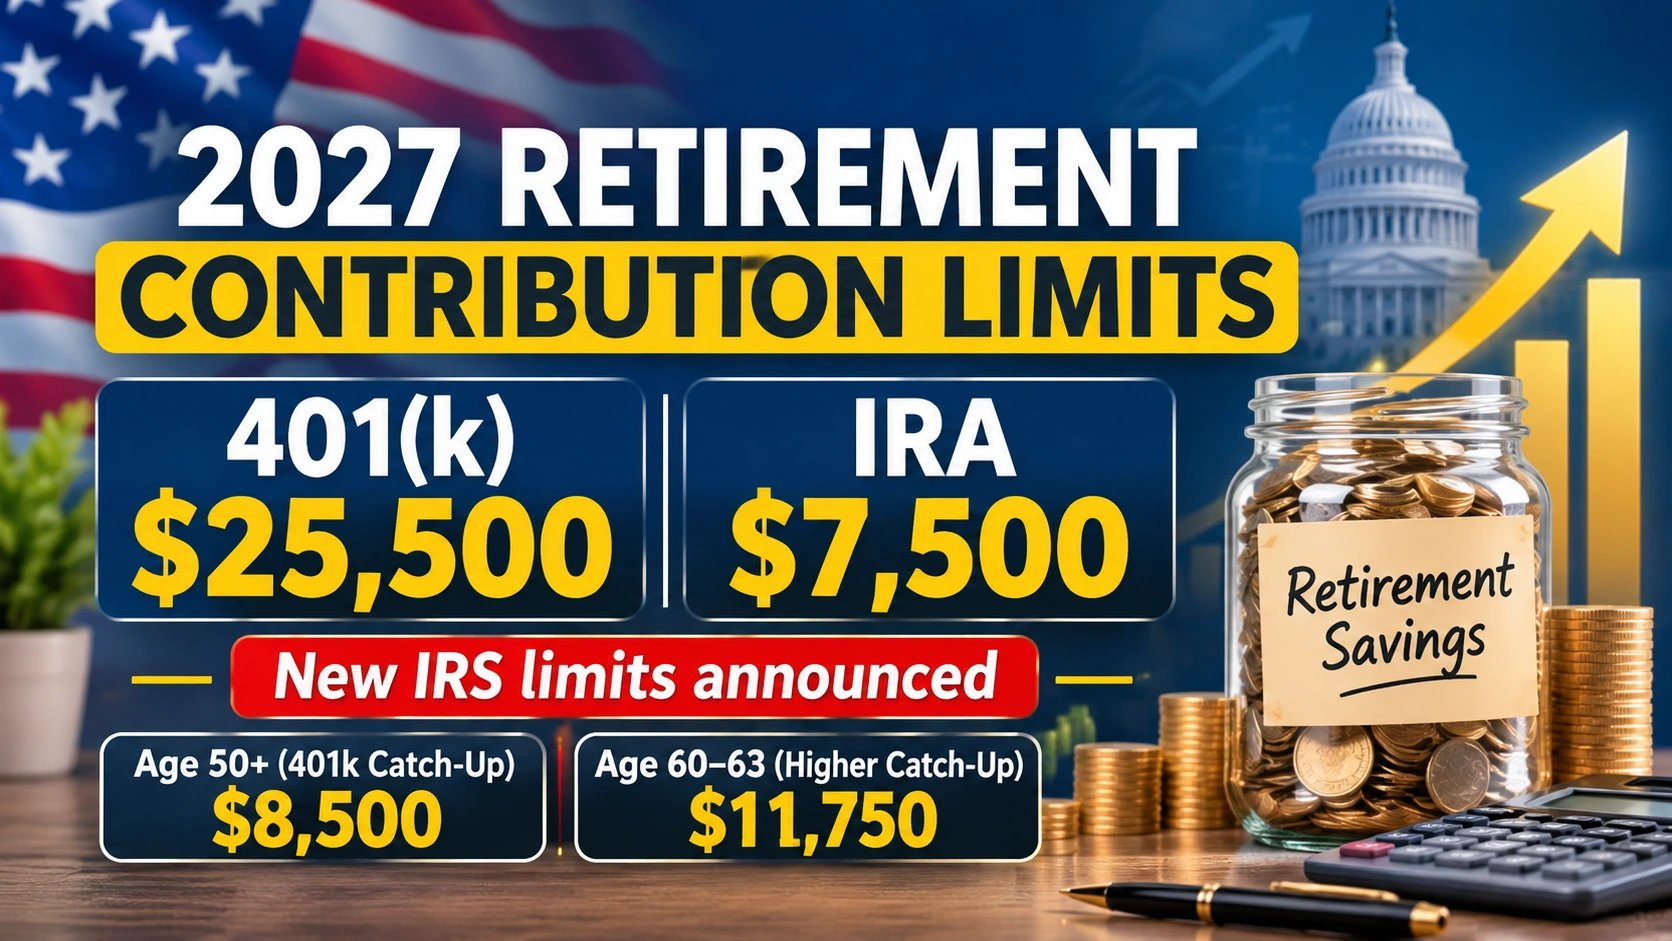
The IRS sets yearly limits on how much you can put into tax-advantaged retirement accounts. On 12 November 2026, the IRS announced the limits for 2027. These are the confirmed figures for both years:
| Account | 2026 limit | 2027 limit |
|---|---|---|
| 401(k), 403(b), most 457 plans, Thrift Savings Plan | $24,500 | $25,500 |
| Catch-up contribution, age 50 and over | $8,000 extra | $8,500 extra |
| Higher catch-up, ages 60 to 63 | $11,250 extra | $11,750 extra |
| Traditional and Roth IRA (combined) | $7,500 | $7,500 |
| IRA catch-up, age 50 and over | $1,100 extra | $1,100 extra |
For every 2027 change, including the new IRA income ranges, read our full guide to the 2027 401(k) and IRA contribution limits, or check the official IRS announcement.
What If You Have Little or Nothing Saved?
If you have little or nothing saved at 30, 40 or 50, do not give up. Being behind a benchmark does not mean you cannot retire; it means you need a plan. Start by working out how much you can save each month, then look for ways to increase it:
- Cut non-essential expenses and redirect the money to savings.
- Increase your income through a raise, a job change or a side hustle.
- Save at least part of every bonus, tax refund or pay rise.
- Pay down high-interest debt so more of your income is free to save.
- Use catch-up contributions once you turn 50.
- Consider working a few years longer, which gives your savings more time to grow and can increase your Social Security benefit.
Conclusion
A simple retirement savings guideline is to have about 1 times your annual salary saved by age 30, 3 times by age 40 and 6 times by age 50. Use these numbers as a starting point, not a test you pass or fail. The best plan fits your income, expenses, goals and expected retirement age. Start as early as you can, take your full employer match, raise your savings rate over time, keep an emergency fund and review your plan as your life changes. What matters most is the action you take today.
This article is for general information only and is not financial advice. For advice on your situation, speak with a qualified financial adviser.
Frequently Asked Questions
How much should I have saved for retirement by age 30?
A common guideline is about 1 times your yearly salary. If you earn $50,000 a year, the target is about $50,000.
How much should I have saved by age 40?
About 3 times your yearly salary. On a $60,000 salary, that is around $180,000.
How much should I have saved by age 50?
About 6 times your yearly salary. Someone earning $70,000 a year would aim for about $420,000.
What percentage of my income should I save for retirement?
Many planners suggest saving about 15% of your pre-tax income each year, including any employer match. If you start late, you may need to save more.