
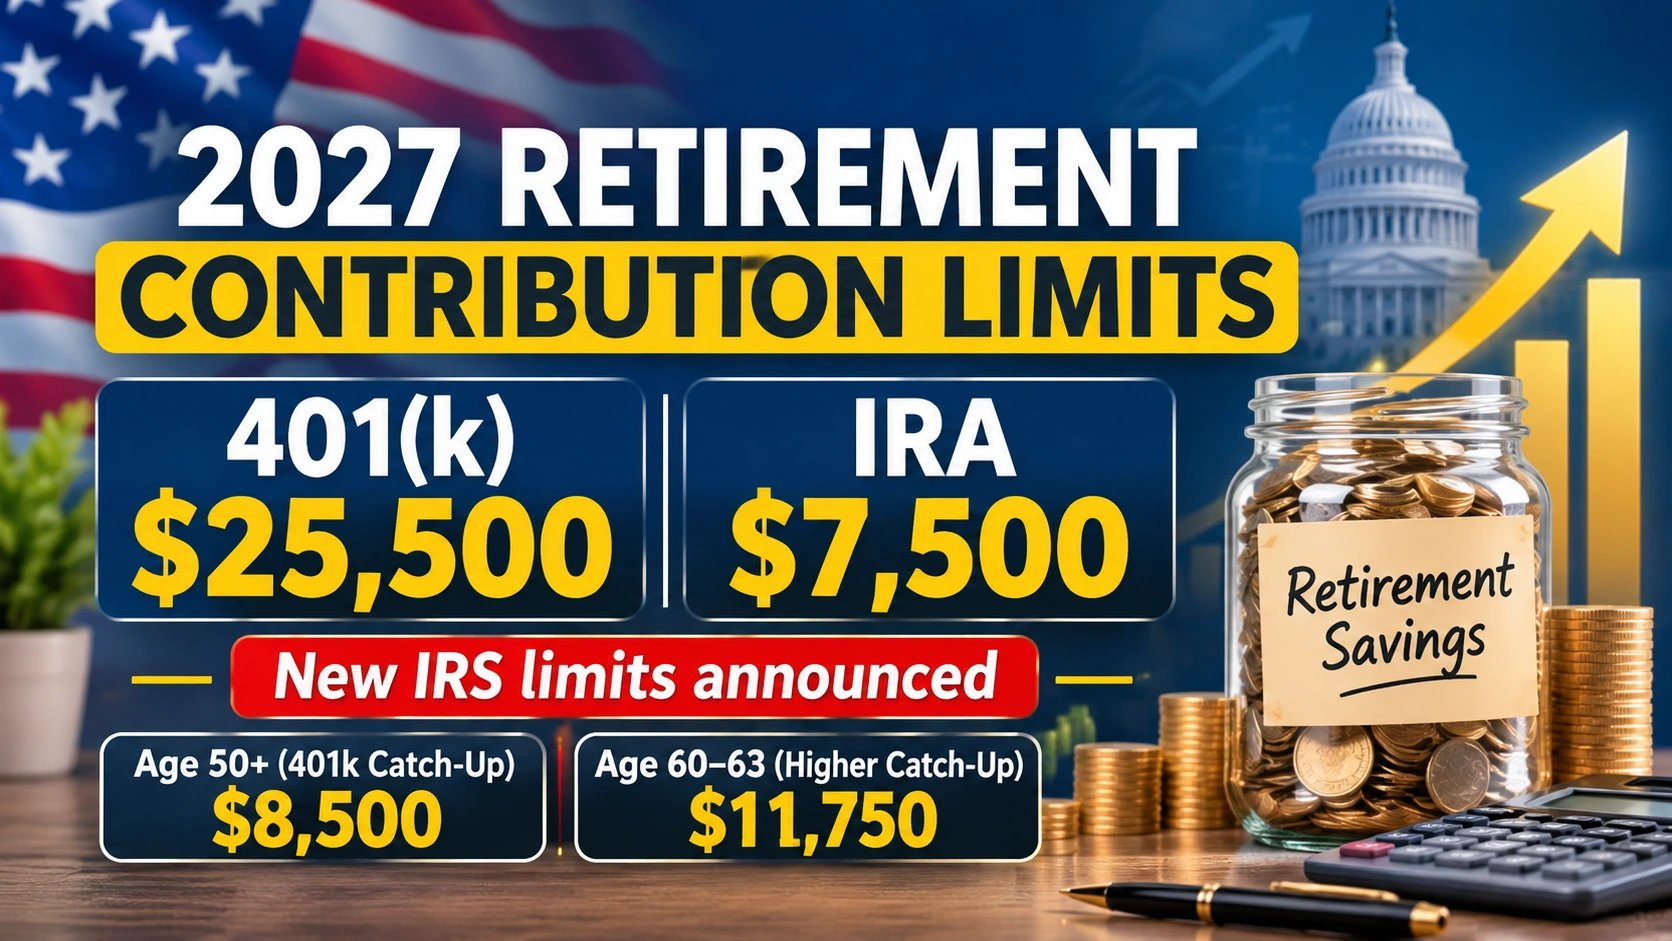


The IRS has raised the 2027 401(k) contribution limit to $25,500, up $1,000 from $24,500 in 2026, while the IRA contribution limit stays at $7,500. Workers aged 50 and over can add an $8,500 catch-up contribution to their 401(k), for a total of $34,000, and those aged 60 to 63 get a higher catch-up of $11,750. The IRS announced the new limits on 12 November 2026 in News Release IR-2026-136 and Notice 2026-66. This guide sets out every key 2027 limit, the new income ranges for IRAs and what to do now to make the most of them.
What Are the 2027 Retirement Contribution Limits?
| Limit | 2026 | 2027 | Change |
|---|---|---|---|
| 401(k), 403(b), governmental 457 and TSP employee contribution | $24,500 | $25,500 | +$1,000 |
| Catch-up, age 50 and over (401(k), 403(b), 457, TSP) | $8,000 | $8,500 | +$500 |
| Higher catch-up, ages 60 to 63 | $11,250 | $11,750 | +$500 |
| Traditional and Roth IRA (combined) | $7,500 | $7,500 | No change |
| IRA catch-up, age 50 and over | $1,100 | $1,100 | No change |
| SIMPLE IRA and SIMPLE 401(k) | $17,000 | $17,500 | +$500 |
| SIMPLE catch-up, age 50 and over (most plans) | $4,000 | $4,000 | No change |
| Annual compensation limit for plan contributions | $360,000 | $375,000 | +$15,000 |
How Much Can You Put Into a 401(k) in 2027?
Your total personal contribution depends on your age in 2027:
| Your age in 2027 | Maximum employee contribution |
|---|---|
| Under 50 | $25,500 |
| 50 to 59, or 64 and over | $34,000 ($25,500 + $8,500 catch-up) |
| 60 to 63 | $37,250 ($25,500 + $11,750 higher catch-up) |
These limits apply per person, not per plan. If you have more than one job or change employers during the year, all your contributions to 401(k) and 403(b) plans share the same $25,500 limit. Employer matching contributions are counted separately, under a higher overall limit for total contributions to your account.
Do High Earners Have to Make Roth Catch-Up Contributions?
Yes, under a SECURE 2.0 rule. Employees aged 50 and over whose wages from their employer in the previous year exceeded a set threshold must make any catch-up contributions as after-tax Roth contributions. Notice 2026-66 raises that threshold to $155,000, up from $150,000. If you are close to this level, check with your plan administrator how your catch-up contributions will be handled in 2027.
What Are the 2027 IRA Income Limits?
The IRA contribution limit did not change, but the income ranges that decide who can deduct traditional IRA contributions or contribute to a Roth IRA all rose for 2027.
Traditional IRA Deduction Phase-Out Ranges
These apply only if you, or your spouse, are covered by a retirement plan at work.
| Situation | 2026 range | 2027 range |
|---|---|---|
| Single, covered by a workplace plan | $81,000 to $91,000 | $83,000 to $93,000 |
| Married filing jointly, contributor covered by a workplace plan | $129,000 to $149,000 | $133,000 to $153,000 |
| Not covered, but married to someone who is | $242,000 to $252,000 | $250,000 to $260,000 |
| Married filing separately, covered by a workplace plan | $0 to $10,000 | $0 to $10,000 |
Roth IRA Income Phase-Out Ranges
| Filing status | 2026 range | 2027 range |
|---|---|---|
| Single and head of household | $153,000 to $168,000 | $158,000 to $173,000 |
| Married filing jointly | $242,000 to $252,000 | $250,000 to $260,000 |
| Married filing separately | $0 to $10,000 | $0 to $10,000 |
If your income falls within a range, you can make a reduced contribution or deduction. Above the top of the range, you cannot contribute directly to a Roth IRA or deduct a traditional IRA contribution.
Who Qualifies for the Saver’s Credit in 2027?
The Saver’s Credit is a tax credit for low- and moderate-income workers who save for retirement. For 2027, the income limits rise to $83,000 for married couples filing jointly (up from $80,500), $62,250 for heads of household (up from $60,375) and $41,500 for single filers and married individuals filing separately (up from $40,250).
What Should You Do Now?
- Update your contribution for January: if you want to max out your 401(k), divide $25,500 by your number of paychecks. With 26 biweekly paychecks, that is about $981 per paycheck before any catch-up.
- Capture your full employer match: at minimum, contribute enough to get every dollar your employer matches.
- Plan your catch-up: if you turn 50, or 60 to 63, during 2027, check that your plan will allow the higher amount.
- Review Roth vs traditional: the new income ranges may change whether a Roth IRA or a deductible traditional IRA makes more sense for you.
- Finish 2026 first: you can still use 2026 limits for this year, and IRA contributions for 2026 can usually be made until the April 2027 tax filing deadline.
For long-term targets, see our guide on how much you should save for retirement by age 30, 40 and 50, and read about portfolio diversification in uncertain markets before choosing investments. Make sure you also have an emergency fund so you never need to withdraw retirement savings early.
This article is for general information only and is not tax or financial advice. Your situation may differ, so check with your plan administrator or a qualified tax professional.
Frequently Asked Questions
What is the 401(k) limit for 2027?
$25,500 for employee contributions to 401(k), 403(b), governmental 457 plans and the federal Thrift Savings Plan, up from $24,500 in 2026.
Did the IRA limit increase for 2027?
No. The IRA contribution limit stays at $7,500, and the catch-up for people aged 50 and over stays at $1,100.
What is the 2027 401(k) catch-up contribution?
$8,500 for workers aged 50 and over, and $11,750 for those aged 60, 61, 62 or 63.
When did the IRS announce the 2027 limits?
On 12 November 2026, in News Release IR-2026-136 and Notice 2026-66.